Week Ending October 23, 2026
DJIA
52,215.16
+0.4% (wk)
S&P 500
7,623.68
-0.5% (wk)
NASDAQ
25,955.34
-0.7% (wk)
A Thursday chip rout and a 7% drop in Meta hand the S&P 500 and Nasdaq a second straight weekly loss while the Dow notches its third weekly gain; Brent crude settles at $116.72, a six-month high, and the 10-year Treasury yield falls below 5% in its biggest one-day drop in more than two years
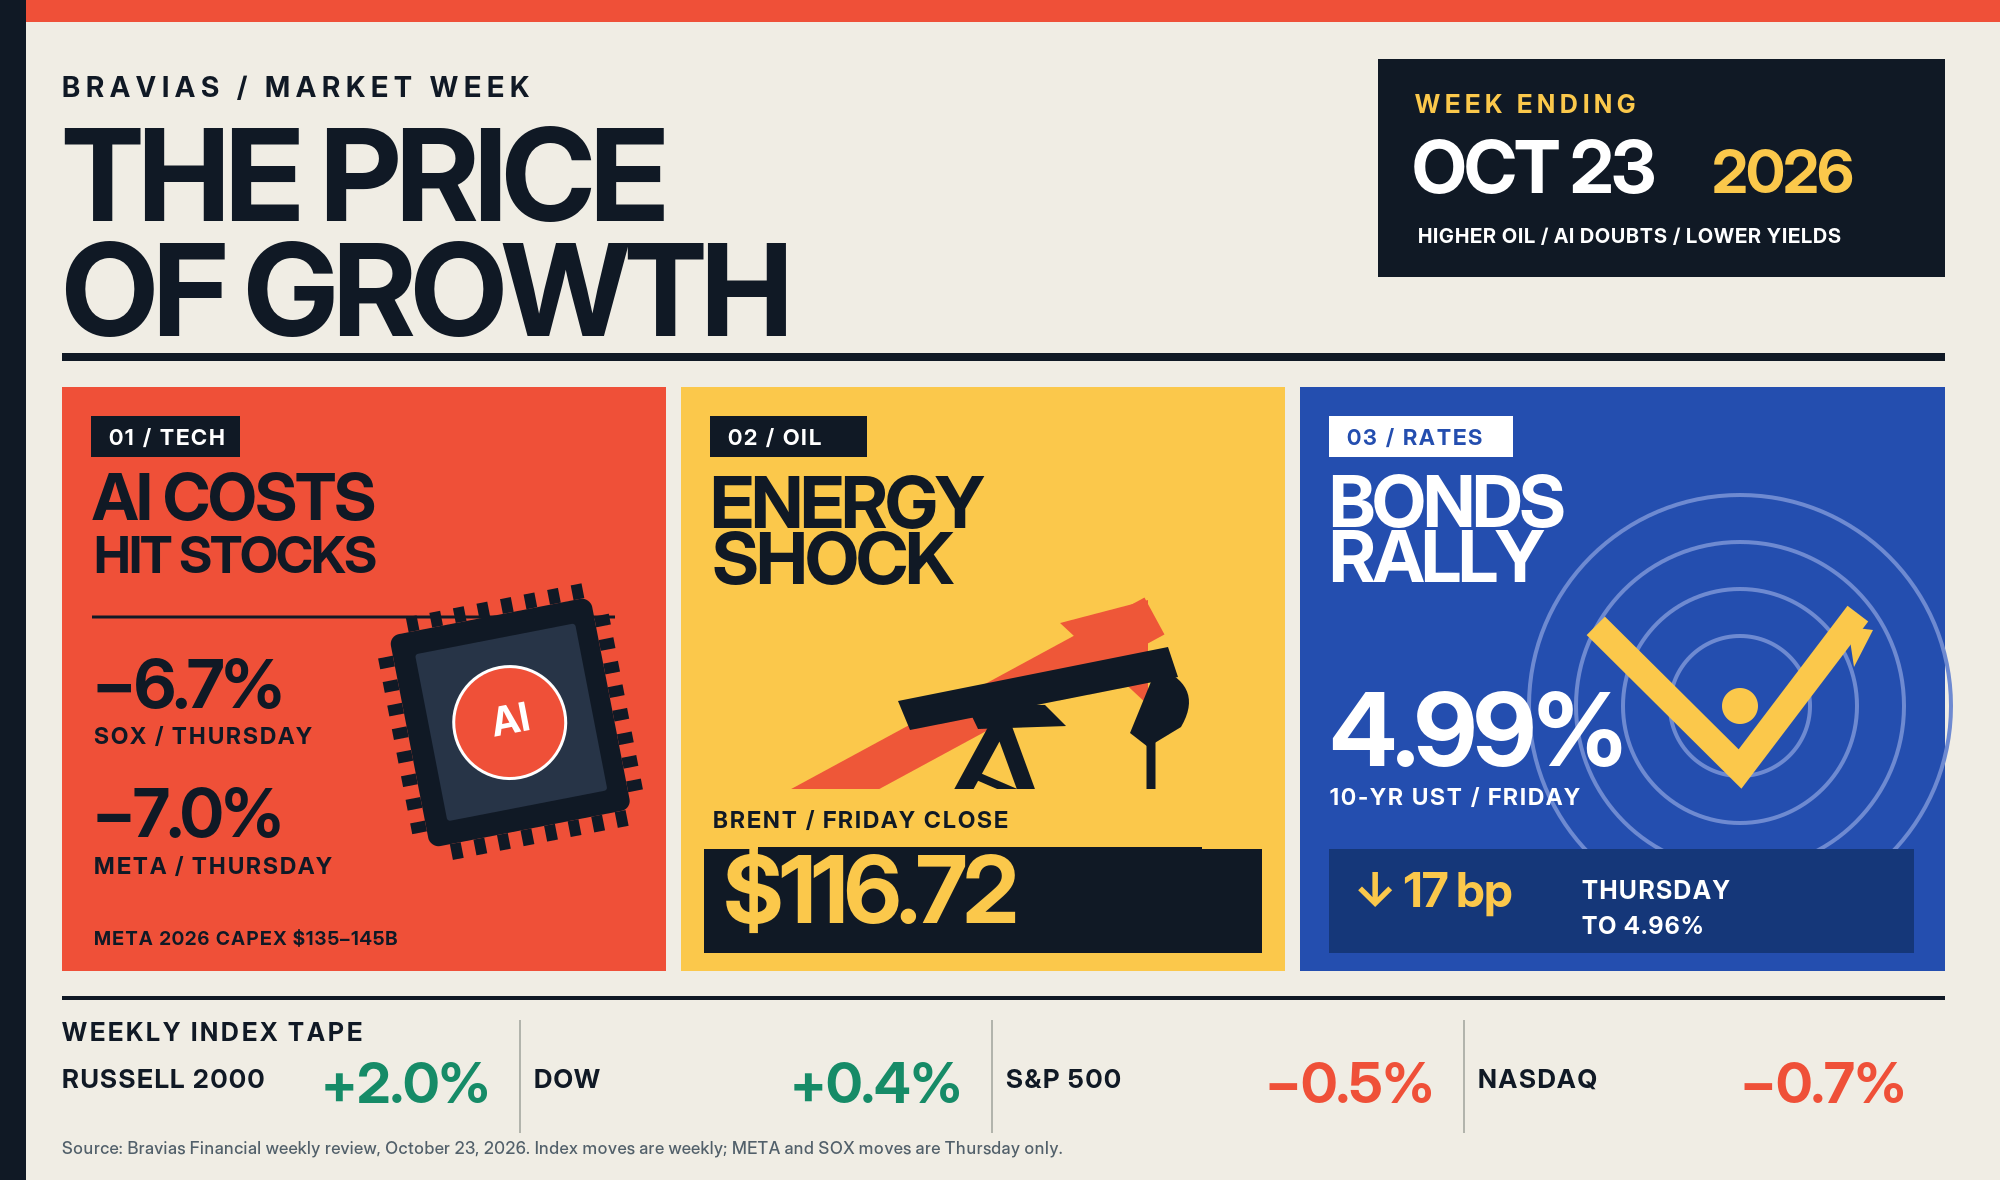
The week started on a strong note and ended with a familiar worry. Tuesday’s rally lifted the Dow 530 points, and strong earnings from SpaceX and Capital One pushed the Nasdaq up 1.1% Wednesday, putting the S&P 500 within reach of its early-October record. Then Big Tech earnings revived doubts about AI spending. On Thursday the Nasdaq fell 2.6%, its worst day since early June, and the Philadelphia Semiconductor Index plunged 6.7%, leaving it more than 26% below its June record. Friday brought more selling, with the Dow dropping 653 points as rising oil weighed on consumer and travel stocks. For the week, the Dow gained 0.4% to 52,215.16, the S&P 500 slipped 0.5% to 7,623.68, and the Nasdaq fell 0.7% to 25,955.34. Small caps were a bright spot, with the Russell 2000 up 2.0%.
Spending versus payoff: Meta beat expectations with $64.6 billion in revenue, but its free cash flow turned negative for the first time in more than a decade on nearly $35 billion of quarterly capital spending, and it raised its 2026 spending outlook to $135 billion to $145 billion. Shares fell 7% Thursday, their largest drop since July. Tesla beat on earnings at $0.48 a share but cut its 2026 capital spending outlook to about $20 billion from more than $25 billion. Netflix beat on profit but fell about 6% after hours Tuesday as it trimmed its ad revenue forecast. The selloff spread quickly: Lam Research fell nearly 12% Thursday on a supply chain warning, Moderna dropped nearly 18%, and Goldman Sachs reported that hedge funds had their worst day since the COVID-era rout, with all three major strategies it tracks losing more than 1%.
Oil up, yields down: Brent crude rose for a third straight week, settling Friday at $116.72, its highest level in six months, while WTI closed just above $103. Thursday’s Houthi attacks on Saudi targets and reports of possible U.S. and Israeli strikes on Iran after the midterm elections drove the gains. Higher fuel costs pushed United, Delta, and American Airlines down more than 4% Friday. Bonds moved the other way as investors sought safety: the 10-year Treasury yield fell 17 basis points Thursday to 4.96%, its biggest one-day drop in more than two years, and ended the week near 4.99%. Futures now price about a 93% chance the Fed holds rates at its October 28 meeting. The University of Michigan’s consumer sentiment index came in at 48.0, still near record lows.
Weekly Performance
| Index | Close | %Chg (wk) |
|---|---|---|
| Dow Industrials | 52,215.16 | +0.4% |
| S&P 500 | 7,623.68 | -0.5% |
| Nasdaq Comp | 25,955.34 | -0.7% |
| Russell 2000 | 2,775.90 | +2.0% |
| 10-Yr Treasury (Thu) | 4.96% | -17 bp in a day |
Big Tech Earnings
| Company | Result | Note |
|---|---|---|
| Meta revenue | $64.6B | vs $63.4B est |
| Meta 2026 capex | $135-145B | Raised |
| Tesla adj. EPS | $0.48 | vs $0.45 est |
| Tesla 2026 capex | ~$20B | From $25B+ |
| Netflix ad revenue (2026) | ~$2.7B | From ~$3B |
Oil, Fed and Sentiment
| Indicator | Level | Note |
|---|---|---|
| Brent Crude (Fri) | $116.72 | 6-month high |
| WTI Crude (Fri) | ~$103 | 3rd weekly gain |
| October FOMC hold odds | ~93% | Meets Oct 28 |
| UMich sentiment (Oct) | 48.0 | Near record lows |
Weekly Movers
| Name | Notable Move |
|---|---|
| Russell 2000 (wk) | +2.0% |
| Blackstone (BX) Thu | +8.4% |
| Palo Alto (PANW) Fri | +7.2% |
| Cloudflare (NET) Fri | +7.3% |
| Chip index (SOX) Thu | -6.7% |
| Lam Research (LRCX) Thu | -11.8% |
| Meta (META) Thu | -7.0% |
| Moderna (MRNA) Thu | -17.6% |
| Netflix (NFLX) after hours Tue | ~-6% |
| UAL, DAL, AAL (Fri) | -4%+ |
Week Ahead
- October 28 FOMC: Markets expect the Fed to hold after September’s hike, with hold odds near 93%. Watch whether Chair Warsh signals that December remains live as oil pushes inflation higher.
- Third-Quarter GDP: The first estimate arrives Thursday, October 29, the day after the Fed decision. A strong reading would support the case for further tightening.
- Earnings Keep Coming: Verizon reports Monday, followed by Coca-Cola, UPS, SoFi, and Robinhood on Tuesday. Telecom investors will also watch reports that SpaceX is in talks to lease cell sites.
- Oil and Iran: Brent at a six-month high puts energy costs back at the center of the inflation story. Any confirmation of new strikes on Iran could push crude higher still.
- Midterm Elections: Voters go to the polls Tuesday, November 3. Expect policy headlines, and possibly volatility, to build through the week.
TERM OF THE WEEK
Free Cash Flow: The cash a company has left after paying for its operations and its capital spending on things like buildings, equipment, and data centers. It is often a cleaner measure of financial health than reported earnings, because it shows how much money is actually available to pay dividends, buy back shares, reduce debt, or keep investing. This week showed why investors watch it closely. Meta beat revenue expectations, but nearly $35 billion of quarterly capital spending pushed its free cash flow negative for the first time in more than a decade, and the stock fell 7%. Tesla reported $1.53 billion of positive free cash flow, though partly because it spent less on capital projects. The takeaway: strong sales can still disappoint if the cost of chasing growth consumes all the cash. When a company raises its spending plans, ask how long it can fund them from its own cash flow before it has to borrow or issue shares.
