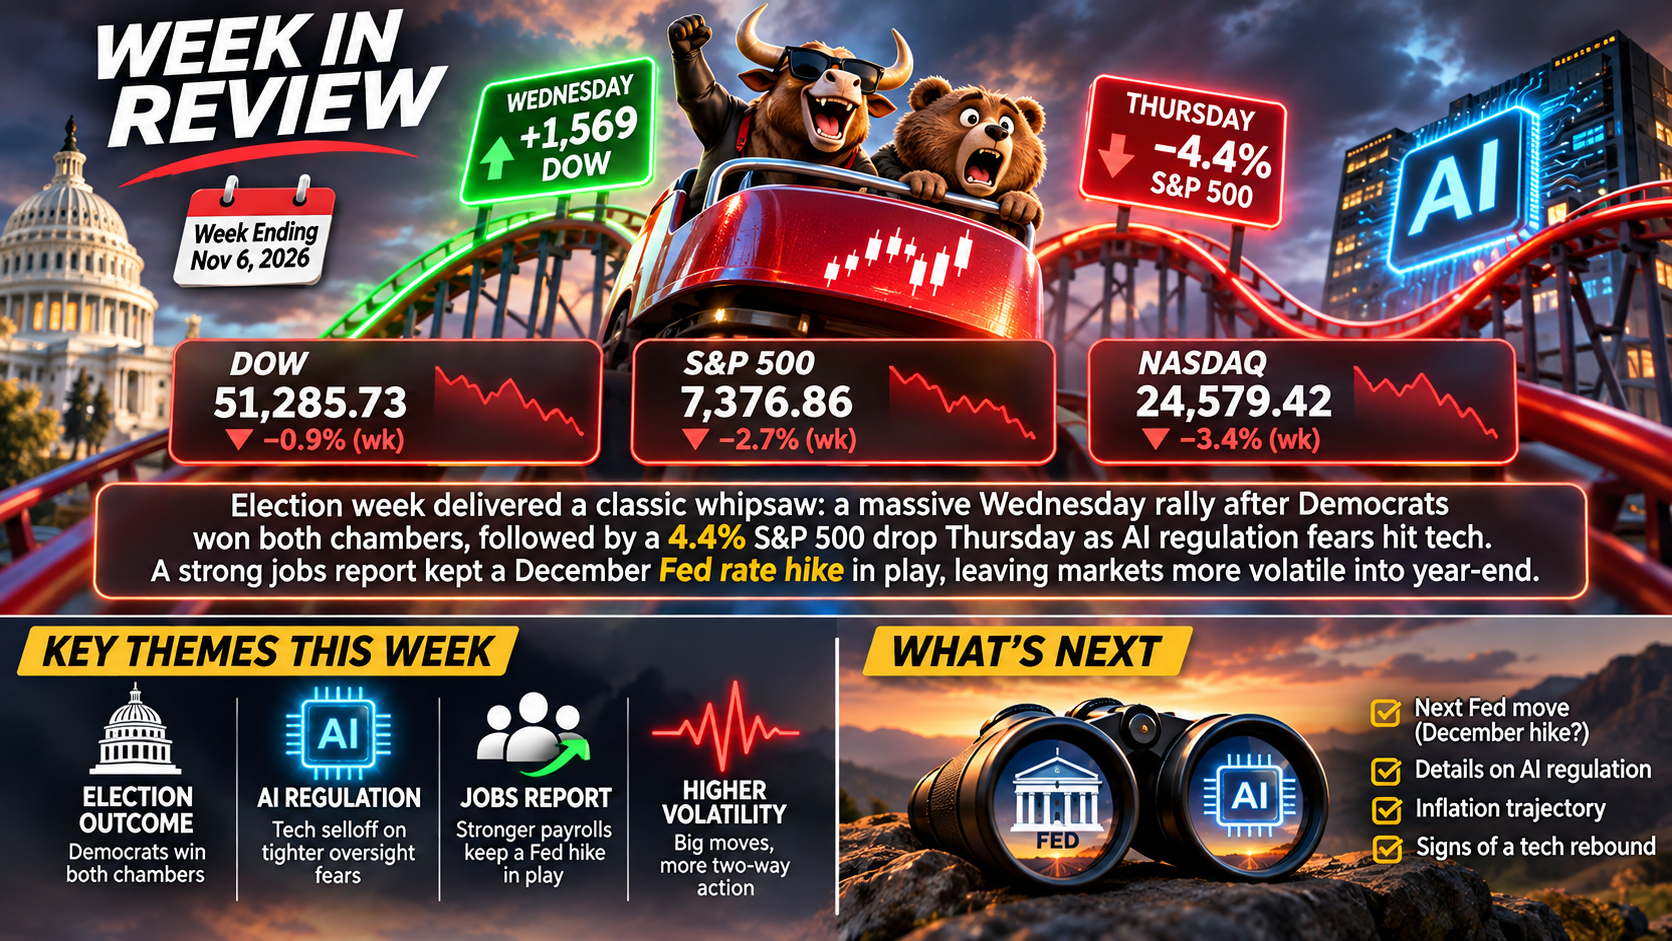
Week Ending November 6, 2026
DJIA
51,285.73
-0.9% (wk)
S&P 500
7,376.86
-2.7% (wk)
NASDAQ
24,579.42
-3.4% (wk)
Democrats win both chambers of Congress, sparking a 1,569-point Dow surge Wednesday and a 4.4% S&P 500 plunge Thursday as AI stocks crater on regulation fears; the Nasdaq enters a correction and falls 3.4% for the week, while a strong jobs report keeps a December Fed hike in play
Election week delivered whiplash. On Wednesday, after Democrats won majorities in both the House and the Senate, the Dow soared 1,569 points, or 3.0%, to 53,356.12, its best day since April 2025, as oil prices collapsed and Apple hit a record high. The mood flipped Thursday. The S&P 500 fell 4.4%, erasing about $3 trillion in market value, and the Nasdaq sank 5.5% for its worst day since April 2025, entering a correction more than 10% below its October 6 record. Every Dow stock and every S&P 500 sector fell. Chips rebounded Friday, but not enough: for the week the Dow slipped 0.9% to 51,285.73, the S&P 500 dropped 2.7% to 7,376.86 in its worst week since June, and the Nasdaq fell 3.4% to 24,579.42, its fourth straight weekly decline.
The AI regulation scare: Thursday’s selloff centered on fears that the new Congress and newly elected state officials will be tougher on the AI build-out. Data center and AI infrastructure stocks began sliding Wednesday after Texas’s governor-elect pledged a moratorium on new data center approvals, and the selling spread across the sector Thursday. The Philadelphia Semiconductor Index fell more than 12%, Nvidia dropped 9.3%, and GE Vernova lost 7.5%. The VIX volatility index jumped about 70% to 28.18. Friday brought partial relief, with the chip index up about 4% and AMD up about 11%, while Airbnb jumped 12% after raising its revenue outlook and Atlassian fell 16% after its results. One strategist called the selloff “a little bit of a knee-jerk reaction,” and others said AI remains the dominant theme in this bull market.
Oil, jobs and the Fed: Oil prices tumbled Wednesday as traders bet that pressure to end the war with Iran will grow. WTI fell 8.3% to $88.12 and Brent dropped 8.7% to $94.62, both at two-month lows. Prices rebounded Thursday after tanker attacks in the Gulf, and the S&P 500 energy sector still fell about 12% for the week, its worst week since April 2025. Friday’s October jobs report was much stronger than expected, with employers adding 165,000 jobs and the unemployment rate at 4.1%. That pushed the odds of a December Fed rate hike to 78% from 70%, according to LSEG, and lifted the 10-year Treasury yield to about 4.86%. President Trump congratulated Democrats on their win but said he would “just veto everything” if they do not work with him.
Weekly Performance
| Index | Close | %Chg (wk) |
|---|---|---|
| Dow Industrials | 51,285.73 | -0.9% |
| S&P 500 | 7,376.86 | -2.7% |
| Nasdaq Comp | 24,579.42 | -3.4% |
| Russell 2000 | 2,754.11 | ~-1.7% |
| 10-Yr Treasury (Fri) | ~4.86% | Rose on jobs |
Election Week Whiplash
| Move | Change | Note |
|---|---|---|
| Dow (Wed) | +3.0% | Best since Apr 2025 |
| S&P 500 (Thu) | -4.4% | ~$3T erased |
| Nasdaq (Thu) | -5.5% | In correction |
| Chip index (Thu) | -12%+ | +4% Fri |
| VIX (Thu) | 28.18 | +70% |
Jobs, Fed and Oil
| Indicator | Reading | Note |
|---|---|---|
| October payrolls | +165,000 | Far above est |
| Unemployment rate | 4.1% | Below 4.2% est |
| December hike odds | 78% | From 70% |
| WTI Crude (Wed) | $88.12 | -8.3%, 2-mo low |
Weekly Movers
| Name | Notable Move |
|---|---|
| Dow (Wed) | +1,569 pts |
| Kyndryl (KD) Wed | +30.1% |
| Apple (AAPL) Wed | +5.3%, record |
| Airbnb (ABNB) Fri | +12% |
| AMD (AMD) Fri | ~+11% |
| Nvidia (NVDA) Thu | -9.3% |
| GE Vernova (GEV) Thu | -7.5% |
| FIS (FIS) Wed | -23.7% |
| Atlassian (TEAM) Fri | -16% |
| Energy sector (wk) | ~-12% |
Week Ahead
- October CPI and PPI: The key inflation reports arrive next week. After a strong jobs report, a hot reading would cement expectations for a December hike.
- Veterans Day (Wednesday, November 11): The bond market is closed, but stocks trade regular hours.
- New Congress, New Policy Risk: Investors will watch for early signals on AI and data center regulation, energy, and trade, and for how the White House responds to a Democratic Congress.
- Can AI Stocks Stabilize? Friday’s chip rebound was a start, but the Nasdaq remains in a correction. Watch whether buyers return after the week’s sharp swings.
- Oil and Iran: Brent fell below $100 as hopes for an end to the conflict grew, but tanker attacks show how quickly prices can reverse. Watch the Qatar-mediated talks.
TERM OF THE WEEK
Market Correction: A decline of at least 10% from a recent peak in a stock, an index, or another asset, but less than the 20% drop that defines a bear market. Corrections are common. They often come after strong rallies, when expectations run high and a surprise forces investors to reprice risk. That is what happened this week. Thursday’s 5.5% drop left the Nasdaq more than 10% below its October 6 record close, putting it in correction territory after election results raised fears of tighter AI regulation. The S&P 500, which fell 4.4% that day, remains above that threshold. Corrections can feel sudden and painful, but historically most have not turned into bear markets, and markets have often recovered within months. For long-term investors, a correction is usually a reason to review your plan and diversification, not to make a rushed decision in the middle of a volatile week.
